Retirement planning involves comparing your current savings, regular contributions, expected expenses, inflation and hypothetical returns. The Retirement Planning Calculator Nepal helps you estimate a projected corpus, an approximate monthly saving toward a target, and possible starting retirement income.
The results are illustrative projections based on the information you enter. They do not predict investment performance or guarantee that a particular lifestyle or financial target will be achieved.
Retirement Planning Calculator Nepal
Illustrative accumulation and withdrawal projections with adjustable assumptions
Enter the retirement age that applies to your own plan or employment terms.
Choose a planning age for the period you want the projection to cover.
Include EPF/CIT/SSF balance, FD, mutual funds, etc.
Use hypothetical rates and compare multiple scenarios. Actual returns vary.
Use a hypothetical rate appropriate to the scenario you want to model.
Inflation changes over time. Review current NRB data and test several assumptions.
The model projects this expense to retirement using the inflation assumption.
📊 Two-Phase Retirement Plan
📅 Life Timeline
| Age | Opening (रू) | Saved/Withdrawn (रू) | Projected Growth (रू) | Closing (रू) |
|---|---|---|---|---|
| Click Calculate to see your retirement plan | ||||
📖 Nepal Retirement Planning Guide
- EPF (Employee Provident Fund): The regular contribution scheme states a 10% employee contribution with a matching employer contribution. Check current EPF rules for eligibility, withdrawal, interest, and benefits.
- CIT (Citizen Investment Trust): CIT offers multiple schemes with scheme-specific rates and terms that can change. Check the official CIT website for current details.
- SSF (Social Security Fund): Formal-sector contribution rules commonly use 31% of basic remuneration: 11% from the employee and 20% from the employer. Verify current coverage, allocation, and benefit rules with SSF.
- Retirement age: Retirement rules differ by employer, occupation, and applicable law. Enter the age relevant to your own plan.
- Inflation: Inflation varies over time. Review current Nepal Rastra Bank data and compare several hypothetical inflation assumptions.
- Tax: Tax treatment and deduction limits can change and depend on eligibility and current law. This calculator does not estimate tax.
- Expense coverage: The calculator estimates a corpus for inflation-adjusted expenses over the selected retirement period using the assumed retirement-phase return.
⚠️ Illustrative projection only. Results depend on the inputs and assumptions selected and do not guarantee retirement income, investment returns, tax treatment, or corpus sufficiency. Verify current rules with the relevant official institutions and consider independent professional advice.
How to use the Retirement Planning Calculator
Retirement planning depends on several uncertain factors, including future expenses, inflation, contribution continuity and investment performance. Use this calculator to compare different scenarios rather than treating one result as a personalized retirement recommendation.
Step 1: Enter Your Age Details
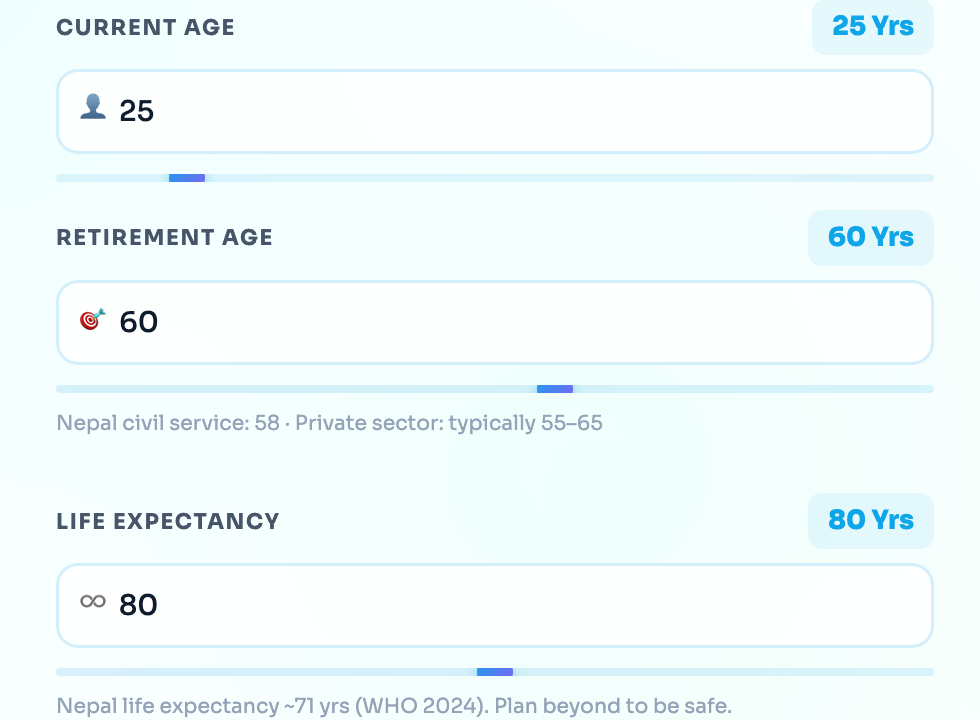
Start by entering the ages that define the projection period.
- Current Age: Enter your age at the beginning of the projection.
- Retirement Age: Enter the age when you plan to end the savings phase and begin the retirement phase. Applicable retirement rules vary by employer, occupation and current law.
- Life Expectancy: Enter the planning age through which you want the withdrawal projection to run. This is a planning assumption, not a prediction of lifespan.
Step 2: Input Your Financial Contributions
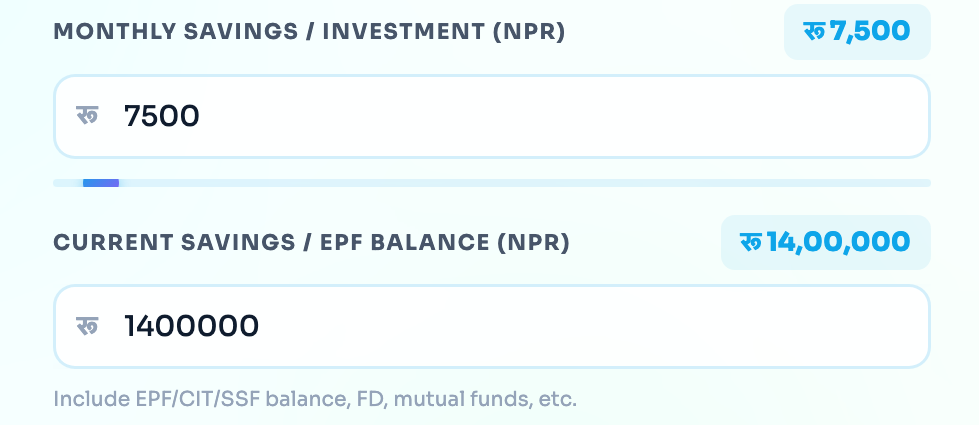
Next, enter the contributions and balances you want the calculator to include.
- Monthly Savings / Investment: In the Retirement Corpus and Retirement Income modes, enter the amount you plan to contribute each month. In Monthly Savings mode, the calculator estimates this amount from your target and other assumptions.
- Current Savings / EPF Balance: Enter the combined current value of the savings you want included, such as EPF, CIT, SSF, fixed deposits or investment balances. Avoid entering the same balance more than once.
Step 3: Estimate Your Returns
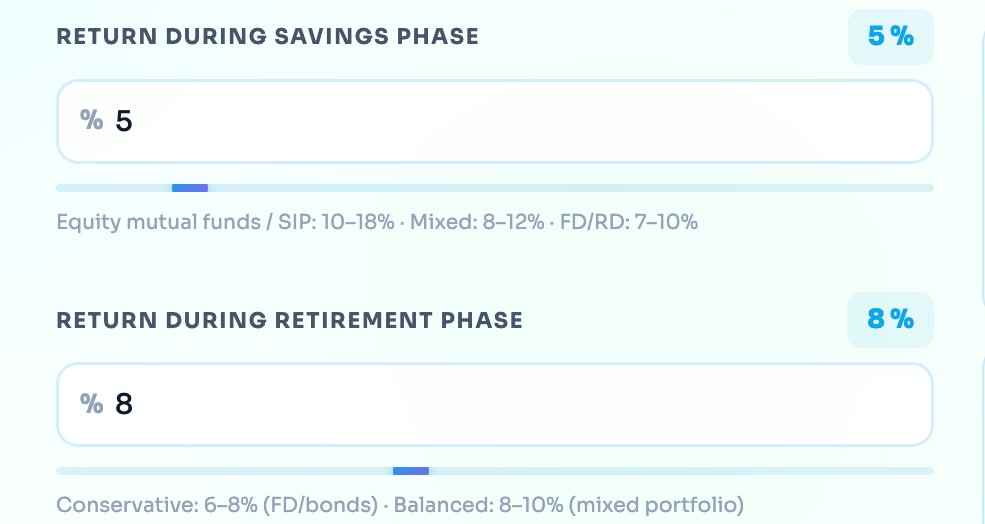
- Assumed Annual Return — Savings Phase: Enter a hypothetical annual return for the years before retirement.
- Assumed Annual Return — Retirement Phase: Enter a separate hypothetical annual return for the withdrawal period.
- There is no standard return that applies to every product or portfolio. Actual returns can change and may be negative. Compare several scenarios instead of relying on one optimistic rate.
Step 4: Factor in Inflation and Expenses
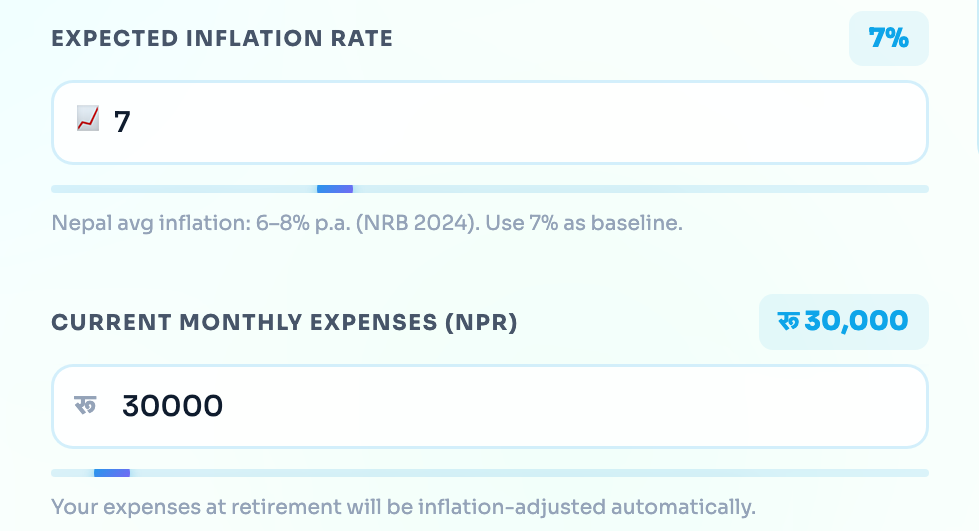
- Assumed Annual Inflation: Enter the inflation rate you want the calculator to model. Inflation changes over time, so compare multiple assumptions and review current data published by Nepal Rastra Bank.
- Current Monthly Expenses: Enter an estimate of your present monthly expenses. The calculator projects this amount to retirement using the inflation assumption.
- The calculated retirement expense is an estimate. Your actual spending may change because of housing, healthcare, family responsibilities, lifestyle and other circumstances.
Step 5: Select Calculate Retirement Plan after completing the relevant fields.
- Retirement Corpus estimates the value that regular contributions and existing savings may reach.
- Monthly Savings estimates a starting monthly contribution toward the entered target.
- Retirement Income estimates a starting monthly withdrawal that is modeled to increase annually with inflation.
The results section displays the projected corpus or income, contributions, projected growth, expense coverage and a year-by-year breakdown. Every result depends on the selected assumptions and may differ from actual investment and retirement outcomes.
The calculator does not include every possible fee, tax, policy change, missed contribution, market fluctuation or personal expense. Review your plan periodically as your income, savings, expenses and goals change.
These are illustrative estimates, not guaranteed retirement outcomes or personalized financial advice. Verify current rules with the relevant official institutions and consider independent professional advice where appropriate.