SIP and lump-sum investing are two ways to buy units of an eligible mutual fund in Nepal. A SIP spreads purchases over time; a lump sum invests available money at once. Neither is always better. The result depends on the fund’s NAV path, fees, your cash flow and how long the money stays invested.
Use the examples below to compare timing risk and cash-flow needs. They illustrate possible outcomes, not a forecast or a promise that either method will outperform.
Understanding the Two Contenders
Both methods can buy the same fund, if its offer document allows each route. The key difference is when the money enters the fund.
- Lump-sum investing: This is exactly what it sounds like. You have Rs. 1,00,000 today, and you use all of it to buy mutual fund units right now.
- SIP (Systematic Investment Plan): Instead of dropping the whole lakh today, you decide to invest Rs. 5,000 every single month for the next 20 months.
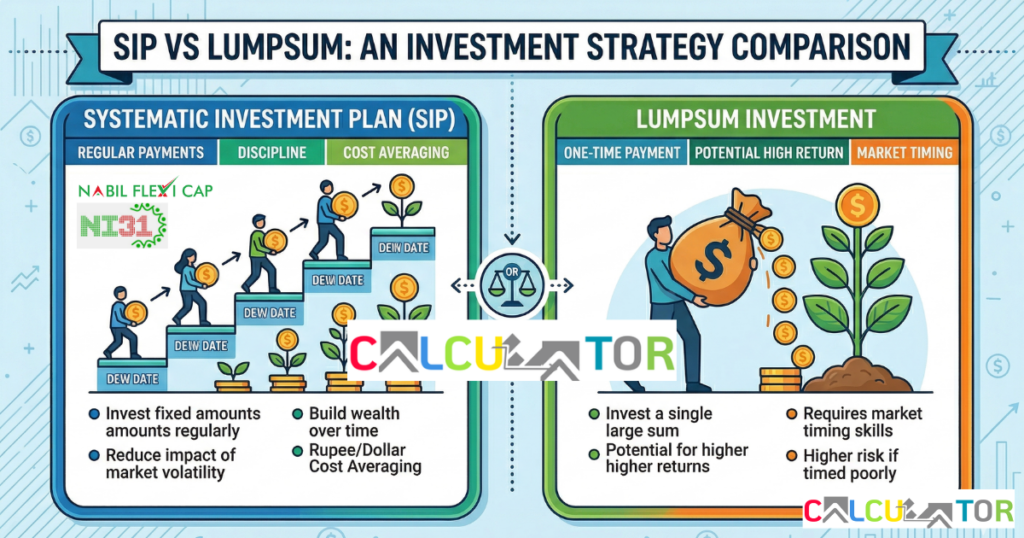
If NAV rises steadily after the start date, investing the same total amount earlier can produce more units’ value. If NAV falls first, spreading purchases may lower the average purchase price. The path and timing matter.
The Case for Lumpsum: Maximising Bull Markets
A lump sum gives the full amount exposure to the fund from the purchase date. In a rising NAV scenario it can outperform the same money invested gradually, because later SIP installments buy units at higher prices. The opposite can happen if NAV falls after the lump-sum purchase.
For example, NPR 100,000 invested at NAV 10 buys 10,000 units before any charges. At NAV 12 those units have a gross value of NPR 120,000; at NAV 8 they have a gross value of NPR 80,000. This illustration is not a return forecast.
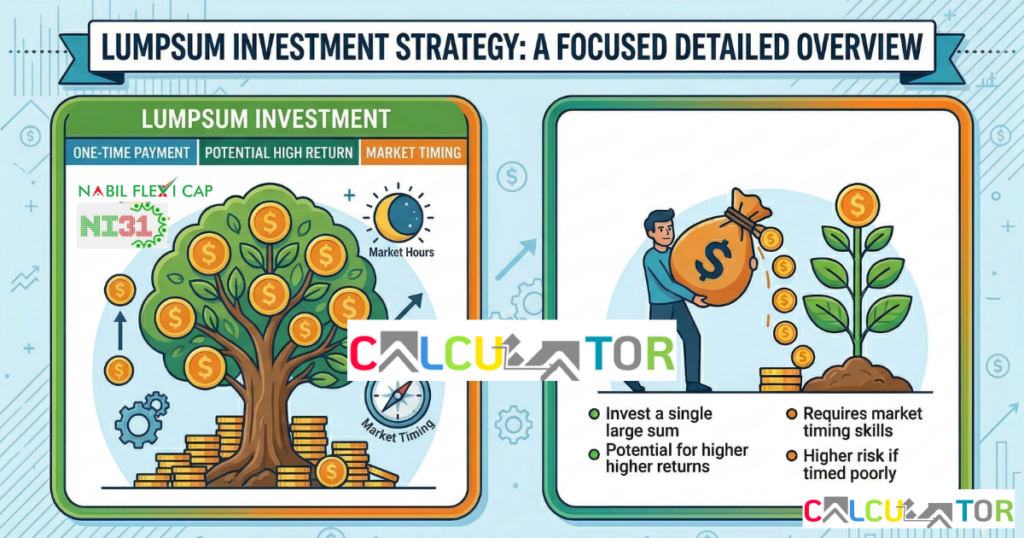
A large one-time purchase concentrates entry-date risk. You cannot know in advance whether the selected NAV is a market low. Also, a mutual fund NAV reflects its underlying assets and is not identical to the NEPSE index.
The Case for SIP: Stress-Free Averaging
A SIP can suit income received monthly because each installment uses money as it becomes available. It reduces reliance on choosing one entry date, but does not remove market risk or ensure a profit.
With a fixed NPR 5,000 installment, NAV 10 buys 500 units and NAV 8 buys 625 units, before fees. Buying more units at a lower NAV can lower the average cost, but losses remain possible and the final value depends on future NAVs.
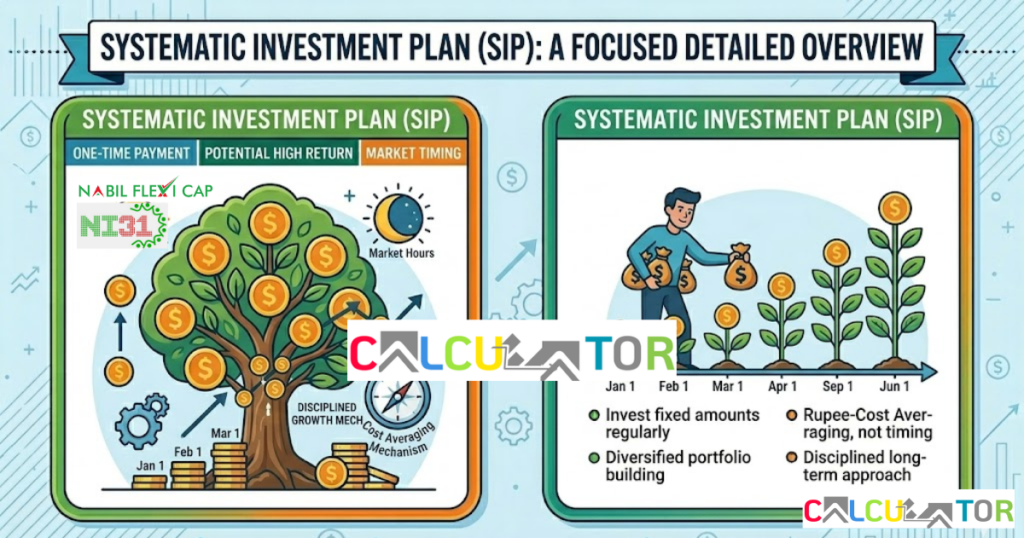
Choose an installment you can afford after essential expenses and emergency savings. If you schedule a debit after payday, check the scheme’s available dates, keep enough balance, and confirm each payment and allotment. Automation can fail.
Which is Better SIP or Lumpsum in a Falling Market?
In a falling market, a lump sum bought earlier loses value immediately as NAV falls. Later SIP installments can buy more units at lower NAVs, but the earlier installments also lose value.
A SIP is not a safety net against losses. Averaging helps only if later NAVs and the eventual redemption value support it; a prolonged decline can leave both SIP and lump-sum investors below their total contributions. Compare outcomes using the same total amount and end date.
Is SIP and Mutual Fund Same? (The Difference Explained Simply)
A mutual fund is the investment scheme; SIP is a schedule for buying its units where offered. A fixed deposit is a different product with different risk and terms, so do not treat its interest rate as a mutual fund return benchmark.
SIP means Systematic Investment Plan. In this article, it is a recurring way to buy units of an eligible mutual fund, not a separate fund or a guaranteed-return product.
Difference Between Mutual Fund and SIP?
To really grasp how your money grows, we need to answer exactly what is the difference between mutual fund and sip. The absolute easiest way to understand it is to separate the product from the process.
- The Mutual Fund (The Product): This is the actual financial asset you are buying. It is a massive, collective pool of money gathered from thousands of everyday investors. Professional fund managers take this giant pool of cash and invest it in a diversified portfolio of shares, bonds, or government debentures.
- The SIP (The Process): SIP stands for Systematic Investment Plan. This is simply your chosen method of buying the mutual fund. It is not an asset itself; it is a payment strategy.
The Ultimate Verdict
Choose based on when your money is available, your need for liquidity and your tolerance for a loss after investing.
Two common situations illustrate the trade-off:
- Regular salary: A SIP can match monthly cash flow and make a repeatable investment habit. It still carries market risk and can lose value.
- Existing lump sum: Investing at once gives immediate exposure but concentrates entry-date risk. Gradual investing may feel easier to manage, although cash held back has its own opportunity cost. Check whether your chosen Nepali fund actually offers a transfer facility before considering one; no debt fund is risk-free.
Conclusion
There is no universal winner between SIP and lump-sum investing. Compare the same fund, total contribution, charges and evaluation date; consider your emergency reserve and time horizon. Past NAV movements cannot tell you which approach will do better next. For Nepal-specific rules, check SEBON’s current regulations and the chosen scheme’s latest documents. NIMB Ace Capital’s Sahabhagita Fund FAQ illustrates how one open-ended fund handles unit purchase and redemption; its terms are not universal.