
Most people researching SIP in Nepal begin with a practical question: “If I invest Rs 5,000 every month, approximately how much could it become after ten years?” The answer depends on the scheme’s NAV movement, distributions, fees and the assumed return used for calculation—none of which guarantees a future result.
This guide explains how SIP investing works in Nepal, what investors should check before registering and how to compare available schemes. It is written for salaried people and other regular-income investors who want to invest a manageable amount consistently.
What a SIP actually is
As mentioned earlier, SIP is the process. It’s a Systematic Investment Plan but not a product you “buy”. It is a method: you put a fixed amount into an open-ended mutual fund on a fixed schedule, usually every month.
A SIP and a recurring deposit can both use monthly payments, but they work differently. A recurring deposit follows bank terms; a mutual fund SIP buys market-linked units whose value can rise or fall.
A recurring deposit is a bank product whose rate, crediting method and maturity terms are set by the bank. Confirm the actual maturity value and early-closure rules in the product document; they are different from a market-linked mutual fund.
Each accepted SIP installment buys mutual fund units at the NAV applicable under that scheme’s allotment and cut-off rules. At a lower NAV, the same amount buys more units; at a higher NAV, fewer. The final value is not guaranteed.
That is the trade in your regular discipline with mutual funds: it has certainty on one side, growth potential and market risk on the other.
A simple example of SIP Nepal
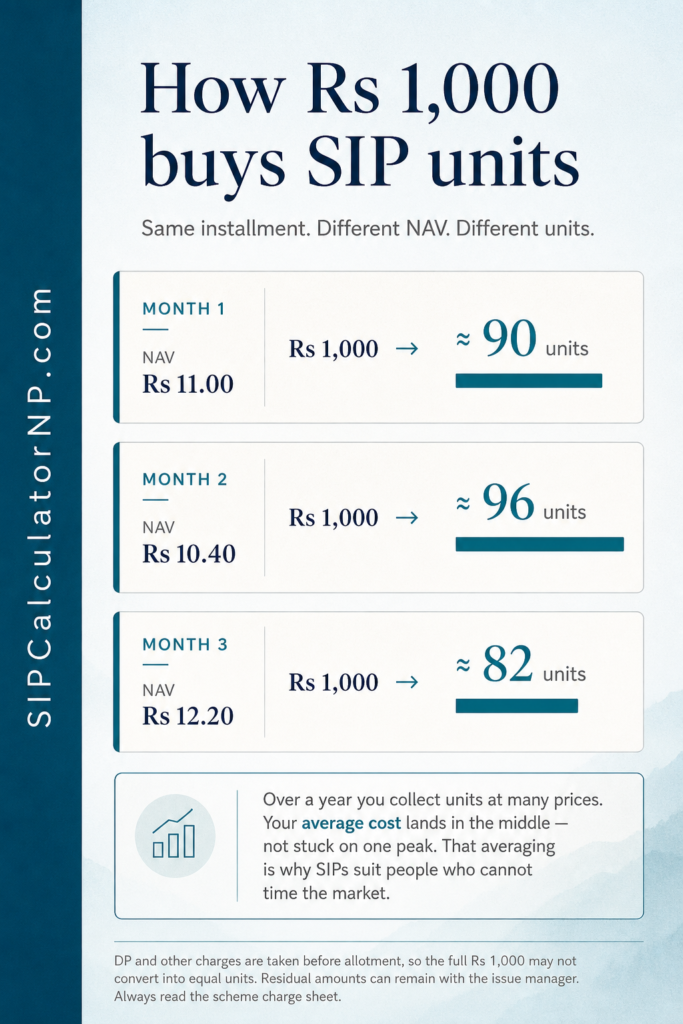
Suppose you invest Rs 1,000.
After charges, the fund allots units using that day’s NAV. If NAV is Rs 11.00, you get roughly 90 units. Next month, if NAV is Rs 10.40, the same Rs 1,000 buys about 96 units. The month after, at Rs 12.20, you might get around 82.
Over a year, contributions may buy units at several NAVs. This spreads entry dates, but it neither guarantees a favourable average cost nor prevents a loss when NAV falls.
When a contribution is accepted, the fund manager allots units at the applicable NAV according to the scheme’s rules. Fund expenses, transaction charges, exit loads and the treatment of any residual balance can vary between schemes. Check the current prospectus, fee schedule and official fund-manager portal instead of assuming that every instalment receives the same deductions.
For whom SIP investing suits in Nepal
I will be direct, because a lot of content pretends SIP is for everybody.
It fits well if you:
- Have a regular salary or predictable monthly income
- Can leave the money invested through market declines and wait for the goal’s timeline, without relying on a guaranteed recovery date
- Want a habit of investing without watching NEPSE every evening
- Do not have a large lump sum, but can spare something every month
It fits poorly if you:
- May need this exact money within one or two years
- Still have no emergency fund — build three to six months of expenses in savings or FD first
- Are carrying high-interest personal debt that costs more than a fund is likely to return
- Cannot tolerate seeing your balance fall temporarily — a decline is possible even with regular investing
Mutual fund NAV can fall, and you may see a statement value below your contributions. If you may need the money soon or cannot tolerate a decline, compare lower-volatility options such as an appropriate bank deposit. Consider liquidity, deposit terms and your goal before choosing.
SIP vs fixed deposit
-
Product
Fixed depositReturn Fixed, known in advanceRisk Very low (bank credit risk)Typical starting point Varies by bankLiquidity Premature withdrawal usually has a costRegulator Nepal Rastra BankBest for Capital you may need, short horizon
-
Product
SIP in an open-ended fundReturn Variable — NAV growth and any dividendRisk Market riskTypical starting point Often from about Rs 1,000/month
NIC Asia ELIS starts from Rs 500/monthLiquidity Redeem units under fund rules and any exit loadRegulator SEBONBest for Money you can leave alone for years
Neither product wins in every situation. Match near-term spending needs to an appropriate liquid or deposit product after checking its terms; use a market-linked fund only for money whose value can fluctuate and whose withdrawal rules you understand.
If you want numbers side by side, run your own amount through the SIP calculator and the FD calculator.
Which banks and capital companies offer SIP in Nepal
The bank name in a scheme’s branding may differ from the fund manager responsible for its portal and records. Confirm the manager and scheme in SEBON’s approved-schemes list, then read the manager’s current offer document, fee schedule and NAV reports. For a concrete illustration of SIP registration and non-guaranteed returns, see NIMB Ace Capital’s Sahabhagita Fund FAQ.
The manager handles scheme operations under the applicable documents. A bank relationship does not make mutual fund returns a bank deposit or guarantee.
Issue manager (capital company) Associated bank (everyday name) SIP scheme(s)
- Issue manager Nabil Investment Banking Associated bank Nabil Bank SIP scheme(s) NI 31, Nabil Flexi Cap Fund
- Issue manager NIMB Ace Capital Associated bank Nepal Investment Mega Bank SIP scheme(s) NIBL Sahabhagita Fund
- Issue manager NMB Capital Associated bank NMB Bank SIP scheme(s) NMB Saral Bachat Fund – E
- Issue manager NIC ASIA Capital Associated bank NIC Asia Bank SIP scheme(s) NIC ASIA Dynamic Debt Fund, NIC Asia ELIS
- Issue manager Kumari Capital Associated bank Kumari Bank SIP scheme(s) Kumari Sunaulo Lagani Yojana (KSLY)
- Issue manager Siddhartha Capital Associated bank Siddhartha Bank SIP scheme(s) Siddhartha Systematic Investment Scheme (SSIS)
- Issue manager Laxmi Sunrise Capital Associated bank Laxmi Sunrise Bank SIP scheme(s) Shubha Laxmi Kosh (SLK)
- Issue manager Machhapuchchhre Capital Associated bank Machhapuchchhre Bank SIP scheme(s) Machhapuchchhre SIP Yojana
- Issue manager Prabhu Capital Associated bank Prabhu Bank SIP scheme(s) Prabhu Systematic SIP Scheme
- Issue manager Sanima Capital Associated bank Sanima Bank SIP scheme(s) Sanima Flexi Cap
- Issue manager Citizens Capital Associated bank Citizens Bank SIP scheme(s) Citizens Sadabahar Yojana
Scheme names and open/close status can change. Before you register, confirm the scheme is currently accepting SIP on the issue manager’s own site.
Portal logins for these managers are collected on the SIP login directory. Payment paths are covered in the SIP payment guide
What you need before you start
- Check the account requirements
Registration requirements differ between schemes and payment channels. Many fund-manager portals request a valid 16-digit BOID so that allotted units can be recorded under the investor’s Demat account.
- Confirm whether MeroShare, CRN or C-ASBA is required
These services may be required for certain registration, verification or payment processes, but they are not universal requirements for every SIP portal. Follow the current checklist published by the selected fund manager.
3. A chosen scheme
Decide before you register anywhere. You register with the capital company that runs that specific fund — not with “Nepal SIP” as a single website.
4. A payment method
Mobile Banking, ConnectIPS, eSewa and Khalti are the major payment gateways in Nepal. Based on the issuing manager, they may have different payment methods and channels. So, based on the supported payment method, you can proceed with the SIP installment payments easily.
Some fund managers and banks support e-mandates, scheduled mobile-banking payments or standing instructions. Availability and setup procedures vary, so use only the payment method shown on the scheme’s official portal or confirmed by the fund manager.
What returns look like — and what they are not
There is no interest rate on a SIP. I say that plainly because “SIP interest rate in Nepal” is one of the most searched phrases on this topic, and the premise is wrong.
Your return comes from NAV movement and any dividend the scheme declares. Both depend on the portfolio. Neither is promised. NAV can fall.
When you use any calculator — including mine — the “expected return” you type in is an assumption, not a forecast. I usually model three cases: conservative, moderate, and optimistic. If only the optimistic case reaches your goal, the plan is fragile.
Dividend history for Nepali schemes: SIP dividend history.
How much should you invest?
Choose a contribution you can sustain after essential expenses, high-interest debt and emergency savings. The scheme’s minimum is only a starting constraint, not a recommendation for your budget.
A framework I use to decide how much to contribute is:
- Cover essentials and high-interest debt first.
- Build an emergency fund of at least six months of expenses.
- Start smaller than your ego wants. Increasing later is easy.
- Stopping after two months often kills the habit.
If your income rises each year, a step-up SIP increases the contribution by a set percentage annually. Compare flat vs stepped amounts on the step-up SIP calculator.
Risks and costs to check before investing
Market risk: Mutual fund NAV can rise or fall according to the scheme’s holdings and market conditions. A longer investment period does not guarantee a positive return.
Redemption conditions: Processing time, exit load and redemption procedures differ between schemes. Read the current scheme documents before assuming that money will be available immediately.
Fund expenses and transaction charges: Operating expenses are generally reflected in the scheme’s NAV, while other charges may apply to particular transactions. Confirm the latest fee schedule with the fund manager.
Portfolio overlap: Holding several schemes does not automatically provide greater diversification. Different funds may own many of the same NEPSE-listed securities.
Behavioural risk: Stopping contributions or redeeming solely because of short-term market movements can affect a long-term plan. Review your goal, financial position and the scheme’s risk before making changes.
Frequently asked questions (FAQ)
The minimum contribution is determined by each scheme and may change. For example, NIC ASIA Capital currently lists Rs 1,000 for regular ELIS SIP and Rs 500 for its Mini SIP option. Verify the current minimum on the selected fund manager’s official registration page before applying.
SEBON regulates the structure, and the units sit in your own Demat account. That is a sound process. The value of those units is not guaranteed.
Usually yes — stop future installments, and redeem existing units under the scheme’s rules. See How to Close a SIP Online.
Depends on the fund manager’s rules for minor accounts and a guardian Demat. Ask the capital company before you assume.
Dividend and capital gains treatment follows prevailing tax rules, and those rules change. Confirm the current position from an official tax source or a qualified adviser — do not rely on a blog for your tax filing.
There is no universal number suitable for every investor. One well-understood scheme may be sufficient for some people, while others may use more than one scheme with different mandates. Compare portfolio overlap, fees, risk, investment goals and the effort required to manage multiple payments before adding another SIP.
No. Buying an individual share means choosing a specific listed company. A SIP in an open-ended mutual fund buys units of that fund at the applicable NAV under its rules; the fund manager decides the underlying portfolio. Some mutual fund units can be traded on NEPSE, so check the scheme type before assuming every fund uses the same purchase route.
A realistic way to start this month
- Decide an amount you can commit for five years without strain.
- Model it in the SIP calculator at a conservative return, then at an optimistic one.
- Pick one scheme and read its official documents — not only a blog summary.
- Check the scheme’s account requirements; obtain a DEMAT account or MeroShare access only where the fund manager’s process requires it.
- Register through the fund manager’s verified portal or branch, then complete the payment method it currently supports.
- If you use a recurring mandate, confirm approval and check every installment debit and unit allotment.
- Review performance periodically, but check payment and allotment records soon after each scheduled installment.
That last instruction is the one I break most often myself, so I will not pretend it is easy.
I, Basanta, am a banker at ‘A’ Class Commercial Bank (Operations) with over four years in Nepal’s banking and financial services sector. I invest in Nepali mutual funds personally and built SIP Calculator NP after finding that most free calculators were built for the Indian market, not Nepal.
This article is educational and is not investment advice. It does not recommend any specific scheme. Mutual fund investments are subject to market risk. Please read the scheme documents and our Financial Disclaimer before investing.

💬 3 Comments